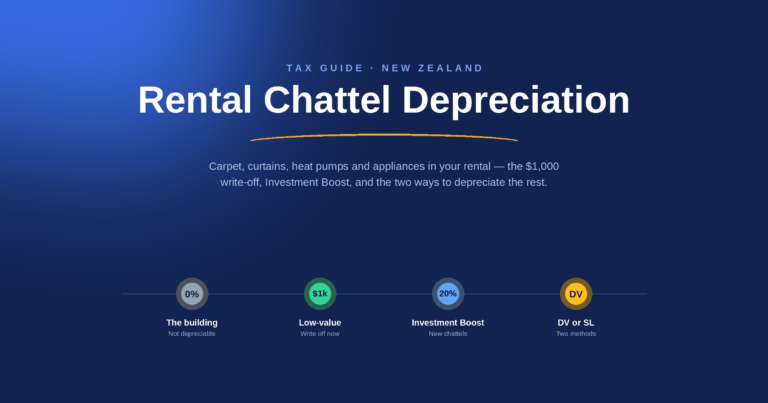
The rental itself doesn’t depreciate for tax, but the chattels inside it do — the carpet, curtains, heat pump, oven and whiteware. How you claim one comes down to its price. If it cost $1,000 or less, it’s simple: the whole cost is claimed as an expense in the year you bought it. Over $1,000, it can’t be written off in one go — it’s depreciated instead, a portion each year over its useful life.
Under $1,000: a new dishwasher for $899. Claim the full $899 as an expense in the year you bought it. Nothing to track after that.
Over $1,000: a new heat pump for $3,450, installed. It’s new, so 20% ($690) is claimed straight away as Investment Boost. The remaining $2,760 is depreciated — at a 20% diminishing value rate, that’s another $552 for a full first year, so $1,242 claimed in year one and the rest spread over the years after.
1. The building vs the chattels inside it
Everything else in this guide builds on one split. The building is depreciated at 0% for tax, so there’s nothing to claim on it. The chattels inside it — the things that aren’t part of the structure — can be depreciated each year.
“Removable” isn’t quite the test, though. Carpet counts as a chattel, but tiles and vinyl flooring don’t; a freestanding wardrobe does, but a built-in one doesn’t. IRD treats anything fitted in as part of the structure — bathroom fittings, kitchen cupboards, doors, plumbing and wiring — as part of the building. Here’s how the common items fall:
Chattels — depreciable
- ✓Carpet
- ✓Curtains and blinds
- ✓Heat pumps
- ✓Hot water cylinders
- ✓Oven, stove and dishwasher
- ✓Fridge, washing machine and dryer
- ✓Loose furniture — beds, sofas, dining tables
- ✓Freestanding wardrobes
- ✓Smoke and burglar alarms
- ✓Clotheslines
Part of the building — not depreciable
- ✗Showers, baths, toilets and vanities
- ✗Kitchen cupboards and benchtops
- ✗Built-in wardrobes
- ✗Tiles and vinyl flooring
- ✗Internal and external doors, including the garage door
- ✗Plumbing and wiring
- ✗Insulation
- ✗Walls, roof and windows
Based on IRD’s interpretation statement on residential rental depreciation (IS 10/01) and its list of rental chattel rates. For anything unusual, check IRD’s Rate Finder or ask your accountant.
2. Chattels costing $1,000 or less
Cheaper items skip the multi-year process entirely. Any chattel costing $1,000 or less can be written off in full in the year you buy it — the low-value write-off. There’s no depreciation schedule and nothing further to track for that item.
The threshold has moved before — it was $500, briefly rose to $5,000 as COVID-19 relief, then settled at $1,000 from 17 March 2021, where it’s stayed since. Worth a quick check against IRD’s own site if it’s been a while.
3. Chattels that came with the property
When you buy a rental, the carpet, curtains and appliances already in it are usually part of the purchase price — and you can depreciate them too. There’s no receipt for them, so their cost is an apportioned value: the share of the purchase price that relates to the chattels.
Your purchase may come with a chattels valuation report you can use, and it’s perfectly fine to set a value for the chattels yourself, based on your own experience. If the sale and purchase agreement puts a value on the chattels, that’s the figure to use.
You can record them one of two ways:
- One combined value — all the settlement chattels as a single entry, with one rate applied to the lot. Quick to set up.
- Item by item — each chattel as its own entry with its own rate. More setup, but more precise, and easier when one of them is later replaced.
Example: say you buy a house built in the early 2000s, and the chattels in it — carpet, curtains, heat pump, kitchen appliances, hot water cylinder — are valued at around $20,000. Entered as one combined value at 20% diminishing value:
| Year | Calculation | Claim | Value left |
|---|---|---|---|
| Year 1 | 20% × $20,000 | $4,000 | $16,000 |
| Year 2 | 20% × $16,000 | $3,200 | $12,800 |
| Year 3 | 20% × $12,800 | $2,560 | $10,240 |
Or the same $20,000 split into individual items, each at its own diminishing value rate:
| Item | Value | Rate | Year 1 claim |
|---|---|---|---|
| Carpet | $8,000 | 25% | $2,000 |
| Heat pump | $4,000 | 20% | $800 |
| Kitchen appliances | $3,500 | 25% | $875 |
| Curtains and blinds | $3,000 | 25% | $750 |
| Hot water cylinder | $1,500 | 13% | $195 |
| Total | $20,000 | $4,620 |
Item by item takes a little more setup, but each chattel gets its own rate, and when one is replaced — say the carpet — it can be written off on its own. With one combined value, you write off just the part of the total that relates to it instead (see section 6).
Chattels that came with the property were already used when you got them, so they’re second-hand — which matters for the next section.
4. Investment Boost — an extra 20% for new chattels
For a genuinely new chattel first used in the rental on or after 22 May 2025, there’s an extra deduction on top of ordinary depreciation: 20% of the cost, claimed immediately. The other 80% then depreciates normally, using whichever method you’d otherwise use.
Investment Boost excludes residential buildings — not the chattels inside them. So a brand-new heat pump, carpet or oven bought for a rental can qualify, but:
- Second-hand chattels bought in New Zealand don’t — including anything that came with the property at settlement.
- Low-value items don’t need it — anything $1,000 or less is already claimed in full.
- If you claim it, the chattel has to be depreciated from there — you can’t take the 20% and then treat the item as non-depreciable.
5. Diminishing value vs straight line
Once a chattel is over $1,000, you pick one of two standard methods. Both spread the same total cost over the item’s life — they just do it in different shapes.
Diminishing value (DV)
The rate applies to whatever value is left each year, so claims start bigger and taper down over time.
Straight line (SL)
The rate applies to the original cost every year, so the claim stays the same each year until it runs out.
Worked example: $4,000 of carpet that came with the property (second-hand, so no Investment Boost — a clean way to see the two methods on their own), at the app’s carpet starting rates of 25% DV and 17.5% SL, full years throughout.
Diminishing value
| Year | Calculation | Claim | Value left |
|---|---|---|---|
| Year 1 | 25% × $4,000 | $1,000 | $3,000.00 |
| Year 2 | 25% × $3,000 | $750 | $2,250.00 |
| Year 3 | 25% × $2,250 | $562.50 | $1,687.50 |
| Year 4 | 25% × $1,687.50 | $421.88 | $1,265.62 |
| Year 5 | 25% × $1,265.62 | $316.41 | $949.21 |
Each claim is worked out on the value still left, not the original $4,000 — that’s why it shrinks every year, and why it never quite reaches zero on its own.
Straight line
| Year | Calculation | Claim | Value left |
|---|---|---|---|
| Years 1–5 | 17.5% × $4,000 | $700 a year | $500.00 after year 5 |
| Year 6 | Only $500 left | $500 | $0.00 |
Same carpet, same cost — but 17.5% of the original cost every year, so the claim stays at $700 until year 6, when only $500 is left. Straight line always finishes cleanly at $0, while the same carpet under diminishing value is still worth $949.21 after five years.
Neither method is a recommendation over the other — the app supports both, and this describes the mechanics, not which to pick. In the year you buy an item, the claim is pro-rated by the number of months you owned it.
A few common starting rates
These are the one-click starting rates offered in the app when you add a chattel — editable, never enforced. IRD’s real rates depend on the exact item, so check anything that matters against IRD’s Rate Finder.
| Chattel | DV rate | SL rate |
|---|---|---|
| Carpet & floor coverings | 25% | 17.5% |
| Curtains & blinds | 25% | 17.5% |
| Kitchen appliances / whiteware | 25% | 17.5% |
| Heat pump | 20% | 13.5% |
| Hot water cylinder | 13% | 8.5% |
6. Replacing, selling or scrapping a chattel
Chattels wear out, and when one is replaced, sold or thrown away, whatever value was still left on it (its adjusted tax value) is compared with what you got for it:
- Sold for MORE than its remaining value — the difference is taxable income (you’re giving back depreciation already claimed). Only the sale price up to what you originally paid counts, so selling for more than the original cost is never taxed on that extra part.
- Sold for LESS, or scrapped for $0 — the shortfall is an extra deduction instead.
Example: the $4,000 carpet above, on diminishing value, is worth $1,687.50 after three years. If it’s ripped up and replaced then, that $1,687.50 is claimed as a deduction in the year it goes, and the new carpet starts its own depreciation from scratch (with Investment Boost, if it’s new).
How Barnaby helps
Rather than keeping a depreciation spreadsheet for each rental, Barnaby keeps a chattel register for every property, under the Depreciation tab.
Adding a chattel asks for what the calculation needs, once:
- Whether you bought it yourself or it came with the property (as one combined value, or item by item)
- Name, cost (or apportioned value) and date
- Whether it’s brand new — for Investment Boost
- Method — low-value write-off, diminishing value or straight line — with one-click rates for common chattels
On the Transactions page, a purchase can be categorised as Chattels / household items ($1,000 or less), claimed straight away, or Chattels / household items (more than $1,000), which prompts you to add it to the register with the details filled in — and links the two so it’s never claimed twice. Pick the wrong one for the amount and the app points it out.
Replacing a chattel links the old and new items, and the old one is disposed of or partly written off in the same step. The register shows each chattel’s deduction and remaining value for the year, worked out live, and the total flows into the property’s annual tax return without re-entering it anywhere.
Step-by-step walkthrough
Here’s the whole thing in Barnaby, start to finish: the prompt on a $1,000+ purchase, the form that fills itself in, chattels that came with the property, replacing one (including writing off just part of a combined value), the register year by year, and disposing of a chattel later.
Already using Barnaby? The written version, with a screenshot for every step, is on the Depreciation tab under Step-by-step guide.
See it for yourself
Track rent, expenses, chattels and your rental’s tax return in one place.
Get startedRunning a business too? The assets & depreciation guide for sole traders covers the business side, including business-use %.
This is general information, not personalised advice. Rates, thresholds and rules above are current as of September 2026, and they change most years — always check current figures at ird.govt.nz or with an accountant before relying on them for a real decision.