As a self-employed sole trader you pay ACC levies yourself — there’s no employer doing it for you. This isn’t a guide to what ACC is or how to make a claim (see ACC’s own overview of what’s covered if you want that) — it’s about how the levy amount is worked out and how you actually pay it.
1. What you pay: three levies
Your ACC invoice is made up of three separate levies, added together:
- Earner’s levy — a flat $1.75 per $100 of liable income (1.75%). Covers non-work injuries: everyday life, home, sport, etc.
- Work levy — varies by your industry’s risk, based on your Classification Unit (CU), which comes from your Business Industry Classification (BIC) code. Covers work-related injuries.
- Working Safer levy — a flat $0.08 per $100 of liable income, collected on behalf of WorkSafe NZ.
These three rates are combined into a single figure — that combined rate applied to your liable income is your total ACC payment. You don’t need to work any of this out by hand: Barnaby calculates your total ACC levy automatically from the income you’ve already entered.
2. How it’s calculated
Your levy is based on liable income — the self-employment income you declared to IRD on your IR3. ACC gets this straight from IRD once you’ve filed.
Formula: (liable income ÷ 100) × combined levy rate
Two thresholds apply for 2026/27:
- Minimum $50,501 — but this only kicks in if you work more than 30 hours a week. If you’re full-time and earn less than $50,501, ACC still levies you as if you’d earned $50,501 — you don’t get charged less just because your actual income was lower.
- Work 30 hours a week or less and there’s no minimum at all — you’re levied on your actual earnings, however low, with nothing topped up.
- Maximum $156,641 — you don’t pay levies on anything you earn above this, full-time or part-time.
The part-time exception only applies if ACC actually has you down as part-time. ACC calculates your levy from your IR3 income plus your employment status on file — if your account still shows full-time, or has no employment status recorded at all, you can be charged the $50,501 minimum even though you genuinely work 30 hours a week or less. Check and update your status in MyACC for Business (register if you haven’t already) — don’t assume it’s been picked up automatically.
3. Finding your Classification Unit (and getting it right)
Your Work levy rate depends on your CU, which comes from your BIC code. Don’t guess this from IRD’s form alone — there’s a dedicated official tool for it: businessdescription.co.nz, built jointly by Inland Revenue, ACC and Stats NZ specifically to help you find the right code by browsing or searching for your actual business activity. The code you give IRD gets passed straight through to ACC, so getting it right here is what gets your Work levy rate right.
You can also check your current CU in MyACC for Business, and contact ACC directly (business@acc.co.nz or 0800 222 776) if it looks wrong.
4. CoverPlus vs CoverPlus Extra
By default you’re on CoverPlus — your levy moves with your actual IR3 earnings each year.
If your income swings around a lot, you can apply for CoverPlus Extra (CPX) instead: you pick a fixed cover amount yourself, and your levy is calculated on that agreed figure rather than your real earnings — so you know your levy cost, and what you’d be paid if injured, in advance.
To apply: log in to MyACC for Business (or set up an account if you don’t have one), complete the CPX application online — choosing your cover amount and compensation option — then accept the offer letter ACC sends you. No separate paper form; it’s all done through MyACC for Business, and cover starts once you accept.
5. When and how you pay
Your first invoice doesn’t show up until the year after you first file a return showing self-employment income — ACC needs that IR3 data from IRD first. After that, invoices land annually, usually July–September.
You can pay:
- In full, or
- By direct debit instalments — 3, 6, or 10 months — set up in MyACC for Business.
6. Income tax treatment
- Your Work levy and Working Safer levy are deductible — they relate to earning your business income.
- Your Earner’s levy is not deductible — it covers non-work injuries, so IRD treats it as a private expense, not a business one. Easy one to get wrong if you’re claiming the whole invoice as one line.
How Barnaby helps
Rather than working any of this out by hand, Barnaby tracks it for you from set-up through to filing.
Enter your BIC code once, in Settings. Barnaby uses it to work out your Work levy rate, combines it with the Earner’s and Working Safer levies and the income you’ve already recorded, and shows you an approximate ACC figure — kept alongside your GST and income tax in the Tax section, not off in a separate system.
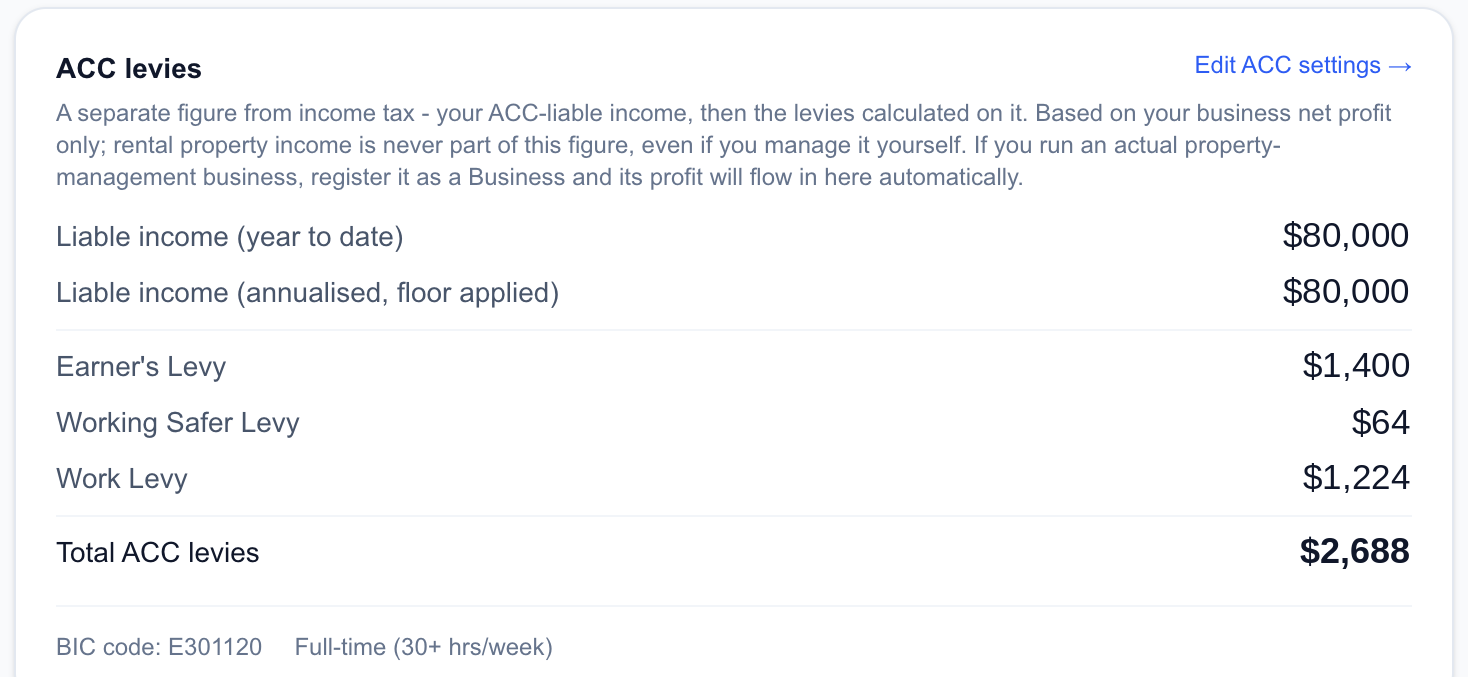
Double-check IRD has your part-time status right, too — if it doesn’t, you can end up levied on the $50,501 minimum even when you genuinely earn less.
Once your real ACC invoice lands and you’ve paid it, just categorise that payment in your transactions as ACC Levy. Barnaby does the rest automatically — it works out the GST portion and claims that as GST, and adds the remainder straight to your claimable expenses, ready for when you file your income tax return.

See it for yourself
Track your GST, income tax and ACC in one place, alongside a rental property if you have one.
Get startedWant the bigger picture first? Read the full Sole Trader Tax in New Zealand guide, which covers income tax, GST, ACC and provisional tax together.
This is general information, not personalised advice. Rates, thresholds and rules above are current as of September 2026, and they change most years — always check current figures at acc.co.nz or with an accountant before relying on them for a real decision.